Home Blog Page 7

What’s happening in the South African mining sector?

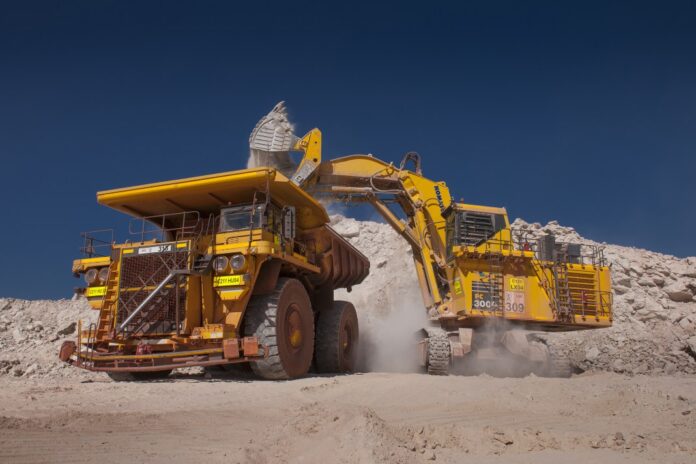
Anglo American is selling. Credit: Anglo American

The board of Anglo American rejected several offers made by BHP to buy the company during 2024. The bid would have excluded Anglo’s two big South African assets, Kumba Iron Ore, pictured, and Anglo American Platinum (Amplats).

Anglo American is selling.

In November 2023 Anglo’s shares came under pressure from the market when the company announced reduced copper targets and major cost-saving measures which included job cuts. Anglo has a long-term strategy to be more focused and consequently is in the process of selling assets and shareholdings in diamonds, coal, nickel and platinum. The portfolio transformation will result in the focus being on copper, premium iron ore and crop nutrients.

Platinum producers have all been under pressure, with Northam Platinum postponing some projects and Sibanye Stillwater laying off staff due to lower global prices. By contrast, the two older staples of South African mining, gold and coal, are making a comeback.

A sale that was first mooted in 2021 was finally resolved in June 2023 when Northam Platinum agreed to sell its stake in Royal Bafokeng Platinum (RBPlat) to Impala Platinum (Implats).

That sale took Implats’ holding in RBPlat to 91% after it had bought 9.26% of the company from Public Investment Corporation (PIC) earlier in the year to give it a majority holding. The RBPlat platinum group metals (PGM) facility, which lies directly south of Sun City, is adjacent to Implats Rustenburg’s land. The Impala Rustenburg operation comprises a nine-shaft mining complex and concentrating and smelting plants. The big sale coincided with a decline in the global prices of some of the PGMs such as palladium and rhodium. Although the long-term prospects for PGMs are good in support of the nascent hydrogen economy, a slowing Chinese economy and the expanded market for electric vehicles are negative factors.

Gold and coal

Gold is popular again as the global price hit record levels because of war and instability in so many parts of the world. In November 2024, Sibanye Stillwater reported a 292% increase in adjusted earnings from its South African gold operations while Gold Fields reported normalised earnings of $900-million in 2023, up from $860-million the year before.

Sibanye Stillwater’s diversification strategy included moving into platinum and this has paid off, despite the current commodity price. While Anglo is doing the opposite in selling many of its assets, it is mirroring one aspect of the Sibanye masterplan by investing in lithium batteries. Sibanye has built up its share in a lithium mine and refinery in Finland to the extent that it now holds 80% of the facility, with the state-owned Finnish Minerals Group (FMG) owning the balance. In 2024, Anglo American signed an agreement with FMG

The world’s deepest mine will be made even deeper.

The Financial Mail’s cover story in March 2024 was about gold’s resurgence and how “local miners are reinventing their business operations to stay in the game”. One example was the R7.9-billion devoted by Harmony Gold to extending the Mponeng mine in Gauteng, which means that the world’s deepest mine will be made even deeper. Harmony bought Mponeng from AngloGold Ashanti. The article further noted plans to list Blyvoor Gold in New York and increased production forecasts from Pan African Resources.

Coal’s resurgence is closely linked to a global rethink about the speed of the transition to cleaner fuels. In South Africa, that means that four coal-burning power plants, Camden, Grootvlei, Hendrina and Kriel, will now only be decommissioned in 2030. The commitment to switch power sources has not changed, but the timeframe has. Coal will continue to be mined for some time to come.
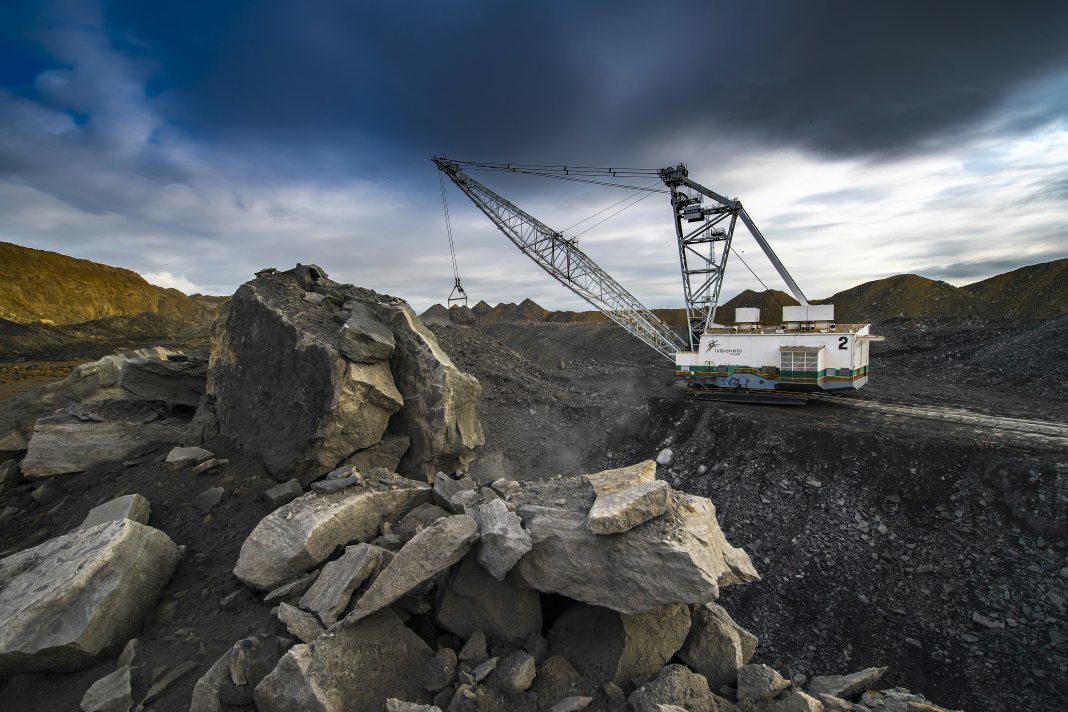
Coal is far from finished. Credit: Thungela Resources

Afrimat, previously listed on the JSE in the “Construction and Building Materials” section, has changed its classification to “General Mining”, a recognition of the company’s ambitious buying programme in the Northern Cape and Mpumalanga. With construction and building now contributing just 20% to operating profit, Afrimat is active in anthracite and iron ore and will further expand into phosphates, rare earth elements and vermiculite. Among its new acquisitions, Afrimat now controls the Nkomati Anthracite mine in Mpumalanga. The mine, which is in the south-eastern corner of the province, has proven resources of 8.7-million tons and upwards of 400 jobs were created over the last two years. Local communities have a 16.1% stake in the relaunched mine and the Mpumalanga Economic Growth Agency (MEGA) holds 34%.

In July 2023, as scheduled, De Beers Group celebrated the beginning of production at its Venetia Mine in the northern part of Limpopo Province. The long-term, $2.3-billion conversion project of the diamond mine to an underground mine began in 2012 and will extend the life of the mine to 2045 or beyond.

In the Northern Cape, the Namakwa Special Economic Zone in Aggeneys is being envisioned as an industrial cluster with the biggest new mine project in the country, the Gamsberg project of Vedanta Zinc International, as the central tenant. The project will 600 000 tons of zinc when phase three is complete.

Copper is one of the most important elements needed to power the renewable energy transformation and so it’s no surprise that areas mined historically for that mineral in the Northern Cape are now back in the news. Batteries need copper, as do systems used to transmit energy from solar or wind sources. Electric vehicles contain an average of 85kg. Copper 360 and Orion Minerals are actively pursuing old sites and new. 


Further online resources:

SMMEs and cooperatives urged to apply for the 2025 Lion’s Den Business Plan Competition

The competition is currently open for this year’s instalment. SMMEs and cooperatives are urged to apply. (Photo Supplied)

EThekwini Municipality invites small, medium, and micro-enterprises (SMMEs) and cooperatives within eThekwini to apply to be part of the 2025 Lions Den Business Plan Competition.

Applications close on 18 April.

The competition aims to foster an entrepreneurial culture while unlocking job creation.

It also offers local businesses the opportunity to access critical development resources and stand the chance to win prizes to elevate their operations.

The competition will be held in three categories namely Emerging Business, Established Business, and Entrepreneurial Excellence.

Competition categories and thresholds are as follows:

  • Emerging Business: SMMEs with viable business ideas and an annual turnover of less than R100 000.
  • Established Business: SMMEs seeking expansion, with annual turnovers between R100 000 and R500 000.
  • Entrepreneurial Excellence: Businesses with an annual turnover of more than R500 000 that have demonstrated exceptional business practices and leadership.

Participants will have the opportunity to pitch their business ideas or expansion plans to a panel of adjudicators.

Winners will receive business development prizes, including funding, equipment, and raw materials to help scale their businesses.

Application forms are available from the Business Support, Tourism, Markets, and Agri-Business Unit located at the Embassy Building, 7th floor, 199 Anton Lembede Street.

Forms can also be obtained from any Sizakala Centre or the SEDA eThekwini Office.

Application forms can also be downloaded from www.durban.gov.za or via this link: 2025 EThekwini Municipality Lions Den Business Plan Competition Application Form.pdf

Applications can be submitted to Yanga Nyakeni at yanga.nyakeni@durban.gov.za

Over the years, the Lions Den Programme has had a significant impact on local SMMEs.

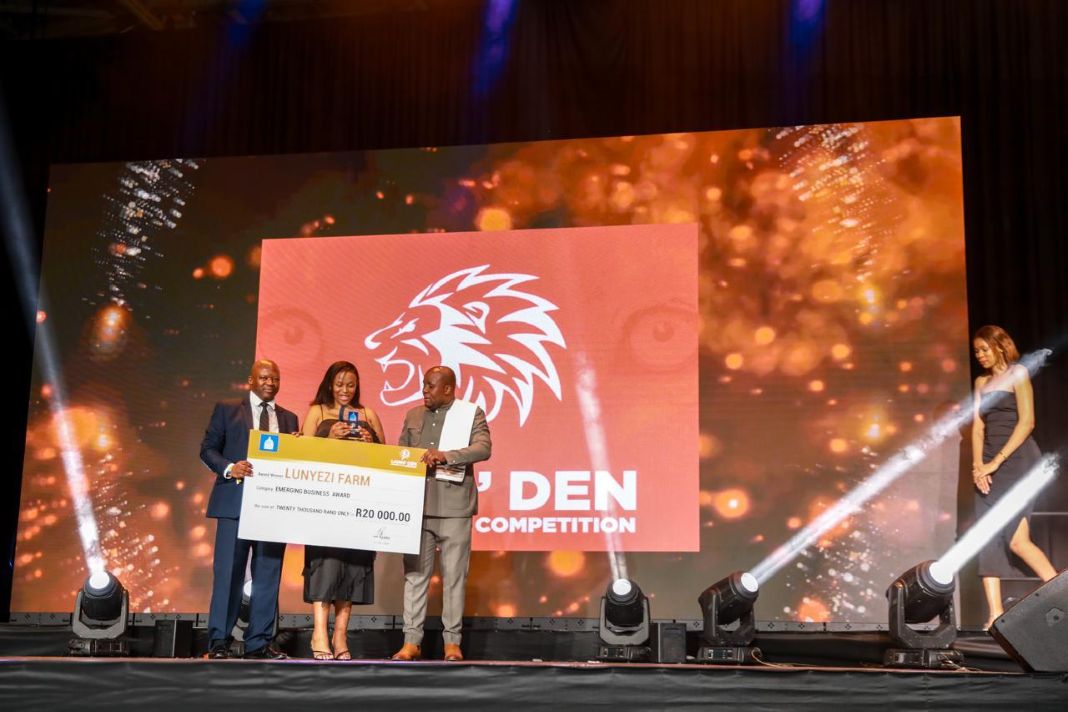
One such success story is that of Samkelisiwe Sithole, the founder of Luhnyenzi Farm, who won the Emerging Business Category last year.

She received R20 000 worth of packaging materials, including a wrapping machine, which she said enhanced her operations.

Commenting on the impact of the initiative Sithole said: “The material lasted three months and helped us appear more professional. Winning this award opened many doors, including recognition from various stakeholders with some approaching us for collaborations. This also boosted faith in our brand as we also offer training.”

Her poultry farming business now employs three people.

Past beneficiaries of eThekwini Municipality’s Lions Den Business Plan Competition have heaped praise on the initiative, highlighting significant growth and new opportunities unlocked following their recognition and prizes received. (Photo Supplied)

For further enquiries, businesses can contact Yanga Nyakeni on 031 309 8280.


Private sector participation in rail and port freight logistics projects launched

Photo Credit: Transnet Port Terminals (TPT)

This launch marks a pivotal milestone in the government’s efforts to collaborate with the private sector to ensure our rail network and our ports resume their rightful place in promoting trade and economic growth.

The Roadmap for The Freight Logistics System in South Africa clarifies that strategic infrastructure such as rail lines and ports will remain in public ownership, as assets belonging to South African people.

At the same time, it paves the way for greater competition in rail and port terminal operations, which will attract private investment and improve our infrastructure to world-class standards. In this context, I believe that the efficiency of the logistics systems is integral to the functioning of all economies. 

Today, I am launching an online Request For Information (RFI) to develop an enabling environment for private sector participation and enhanced investment in rail and port infrastructure and operations.

As you are all aware, South Africa’s rail and port infrastructure faces substantial challenges, including declining performance; theft and vandalism; under-investment, and operational inefficiencies. All of these hinder trade and economic growth.

The limited availability of state resources to fund infrastructure development and address backlogs has intensified these challenges, severely restricting the ability of state-owned entities to fulfill their critical mandates.

Together with Transnet, Government has received numerous unsolicited proposals from the private sector offering investment, skills, and expertise to support the rehabilitation and reform of our struggling rail and port systems. 

This overwhelming interest has made it clear that the Department and Transnet must engage in broad and inclusive market engagement before issuing Requests for Proposals (RFPs) in August this year. These are not formal procurement processes in themselves but a mechanism to understand and source information from the market.

To ensure these RFPs are well responded to, government recognises the importance of understanding the freight logistics landscape through the perspective of interested and affected parties, so that our solutions that are both effective and sustainable.

In this initial phase of Private Sector Participation, the RFI focuses on the following corridors:

  • Northern-Cape to Saldanha Bulk Minerals Corridor primarily for iron ore and manganese exports, and the Northern-Cape to Nelson Mandela Bay Corridor, primarily for manganese exports. 

This includes the complete pit-to-port rail, port, terminal infrastructure, and equipment supporting the transport of iron ore from mines in the greater Sishen–Postmasburg region to the Port of Saldanha, as well as the movement of manganese from mines located between Hotazel and Postmasburg to the Port of Saldanha, and to the ports of Port Elizabeth and Ngqura in Nelson Mandela Bay, and the back of port 
arrangements.

  • Limpopo and Mpumalanga to Richards Bay Bulk Minerals Corridor PSP Project for coal and chrome exports, including provision for magnetite exports in port.

This includes the full pit-to-port rail, port, and terminal infrastructure and equipment supporting coal exports from mines in Lephalale, Limpopo; chrome exports from the ‘Western Limb’ mines in the  Rustenburg-Brits region in North West; and coal exports from various mines across Mpumalanga and KwaZulu-Natal to the Port of Richards Bay. Particular attention is given to the Bayvue precinct, where non-RBCT coal, chrome, and magnetite are handled through the Dry Bulk and Multi-Purpose Terminals, and the back of port arrangements.

  • Intermodal Supply Chain PSP Project focused on the container and automotive sectors, including the potential designation of the South African container port system as a regional transhipment hub for major shipping lines.

This includes the port, container and automotive port terminals, back-of-port arrangements, and railway and inland terminals for the Gauteng—Durban port (KZN), Gauteng—Eastern Cape (East London, Port Elizabeth, Ngqura), and Gauteng—Western Cape (Cape Town) corridors.

The RFI represents a pivotal step forward in our shared commitment to building a 21st-century transport system that goes beyond mobility to strengthen industrial competitiveness, deepen regional integration, and drive inclusive economic growth. 

It will enable us to articulate the challenges in a structured and coherent way, clearly defining their scope, context, and impact to inform the development of focused, strategic, and sustainable solutions. In this regard, the DoT will ensure that the views of a range of other stakeholders are brought into the deliberations, including organised labour.

Capacitating the Department for Private Sector Participation 

In line with the Private Sector Participation envisioned in the White Paper on the National Rail Policy, Cabinet approved a PSP Framework in 2023 to guide private sector involvement across the logistics sector value chain. The Framework mandates the Department of Transport (DoT) to establish a dedicated PSP Unit to enhance state capacity and provide support to Transnet and PRASA in the procurement of potential PSP projects.

The Department is in the final stages of concluding a Memorandum of Agreement with the Development Bank of Southern Africa (DBSA) and the National Treasury, appointing DBSA as the hosting institution for the Unit.

We have set up an interim PSP Unit within the Department, comprising a team with extensive expertise in structuring PSP contracts and procurement. 

In collaboration with Transnet, the interim PSP Unit has developed the Rail Freight and Port RFIs.

What happens next in the RFI phase?

As the RFI is part of a research and consultation process, all information submitted will be treated with strict confidentiality and used exclusively to inform the development of potential PSP projects. Participation in the RFI offers a valuable opportunity to help shape future initiatives.

The RFI must be completed online and can be accessed through the Department of Transport’s website or directly at www.psp-rfi.co.za. The portal will remain open for eight weeks, from 24 March to 9 May 2025.

Submitted responses will be reviewed and feedback will be provided.

Following the conclusion of the RFI phase, the Request for Proposal (RFP) will be undertaken through the PSP Unit. The PSP Unit and Transnet will develop the policy-aligned PSP Programme, which will enter the formal procurement phase from the end of August 2025. 

This work is guided by the following principles:

  • Reform Transnet in accordance with the Cabinet-approved Roadmap for Freight Logistics;
  • Ensure a just transition to a reformed rail and port logistics system, prioritising maximum job retention for employees of Transnet and PRASA and in this regard we have set up a joint work stream to consult organised labour as the process unfolds;
  • Safeguard immovable assets by retaining them under state ownership for the benefit of future generations and preventing the balkanisation of the rail and port system as has occurred in other countries;
  • Actively promote localisation, industrialisation, and support for key sectors such as steel production and local rail manufacturing;
  • Demonstrate our commitment to Broad-Based Black Economic Empowerment and gender equality by providing strong support to new and emerging players in the rail and port sectors, including SMEs and SMMEs.

In closing

I encourage all Interested and Affected Parties to actively engage in this RFI process, contributing to the PSP Unit’s efforts in shaping the potential PSP Programme of Projects and designing future bid packages for procurement. 

In May 2025, the Department will release the second batch of the RFI which will be focused on passenger rail initiatives, together we can achieve more.


Junior Indaba 2025

Resources 4 Africa is pleased to announce the 11th edition of its annual Junior Indaba, taking place on 27 & 28 May 2025 in Johannesburg. 

Please note that the 2025 Junior Indaba will be held at the Houghton Hotel, Houghton Estate, Johannesburg.

The Junior Indaba is a popular meeting place for junior miners and is enjoyed by all for its incisive, informative and frank discussions tackling the challenges of and opportunities for junior mining and exploration in South Africa and elsewhere in Africa.

Discussions will be framed within the global geopolitical, supply chain and energy shifts taking place and their impact on junior mining. Topics under discussion will include the demand for critical metals, the global outlook for commodities, investors’ perspectives on junior mining projects, ESG considerations and much, much more.

Attend and participate in the all-important conversations which will address questions including:
  • How can we create an enabling environment for junior mining and exploration in South Africa?
  • What are the latest updates on the South African cadastral system?
  • How can junior miners and investors manage the risks of operating/investing in Africa?
  • How are juniors addressing the challenges of ESG requirements and energy security/transition concerns?
  • How can juniors overcome the obstacles to obtaining financing for their projects?
  • What is the role of junior miners in meeting the demand for critical minerals and metals?
  • What lessons can be learned from successful junior miners who have managed to successfully get a project off the ground?
  • What technological innovations can be implemented for junior mining and exploration projects?
  • And much more…

Find out and register here: https://www.juniorindaba.com/

SAPICS Conference 2025

Discover the Future of Supply Chain at the 2025 SAPICS Conference

Supply chain professionals from around the world and across industries will gather at Century City Conference Centre, Cape Town this June for SAPICS 2025!

The SAPICS Annual Conference, Africa’s leading event for supply chain professionals, is proud to host Demand Driven World for the first time in its history.

Why Attend?

  • Two Events, One Destination: Enjoy full access to the full conference programme, including both SAPICS and Demand Driven World sessions, with a single registration.
  • Unparalleled Learning Opportunities: Explore diverse topics and groundbreaking insights from global supply chain leaders.
  • Expanded Networking: Connect with a broader community of industry professionals in one place.

Join us as two powerful events come together to create a transformative experience for the supply chain community. Don’t miss this historic opportunity to expand your knowledge, build connections, and shape the future of the industry.

Register now to be part of SAPICS 2025 and Demand Driven World – one incredible destination for supply chain excellence and discover true Innovation in Motion!

www.conference.sapics.org

Small businesses need supply chain skills to survive

The success of small businesses – which are the backbone of South Africa’s economy – is being jeopardised by a lack of resources, skills and support in the critical area of supply chain management, according to supply chain industry body SAPICS.

“Small, medium and micro enterprises (SMMEs) have a crucial role to play in the national economy as employers that can fight the country’s dire unemployment rate and drivers of inclusive economic growth. A major factor in the growth and development of SMMEs is an understanding of operations and supply chain management best practices, but they are falling short and big business needs to step up,” says SAPICS president MJ Schoemaker.

“Small businesses have so many responsibilities, and so many things to consider, that the essential supply chain function is often overlooked. But it can make or break the business and is increasingly important in today’s complex and volatile business environment,” she states.

Corporates can support their suppliers with SAPICS Small Business Hub sponsorship

Schoemaker says that the SAPICS training and support programme for SMMEs offers a solution. A vital lifeline for small businesses that must navigate the turbulent supply chain landscape, the SAPICS Small Business Hub is also a valuable conduit for corporate businesses to support SMMEs and participate in the development of their suppliers. SAPICS is urging corporates to sponsor Small Business Hub membership for their suppliers. “Businesses can earn Enterprise and Supplier Development (ESD) points while empowering and uplifting SMMEs and upskilling their own supplier base,” Shoemaker expands.

“Usually, training for SMMEs focuses on aspects such as marketing and finance, leaving operational skills undeveloped. To survive and thrive, SMMEs need to address the knowledge gaps that exist, including in supply chain management.”

For an annual membership fee, SMMEs can join the SAPICS Small Business Hub and reap the benefits of skills development and knowledge sharing activities like workshops and webinars. They can expand their professional network and have regular face to face and online interaction with the SAPICS supply chain community across Africa. They can enjoy discounted registration fees for industry events, including the annual SAPICS Conference, the leading event in Africa for the supply chain profession.

The topics covered in SAPICS’s skills development events specifically for SMMEs include introductions to supply chain management, demand planning, and sales and operations planning. Case studies and success stories are covered and SMMEs receive advice from industry leaders. Accredited education programmes are also offered and can be sponsored by corporates to grow and develop their suppliers. These focus on specific aspects of supply chain management – like warehouse control, inventory replenishment principles, operational planning and scheduling, lean manufacturing principles and supply chain and materials management – as well as general entrepreneurial topics like business management and basic finance.

A SAPICS SMME Support Line enables small business owners to get advice and assistance.

“When it comes to reaping the benefits of supply chain optimisation – including efficiency enhancements and cost savings – SMMEs are being left behind, but we can change this, and corporates have a role to play,” Shoemaker stresses.

For more information on the SAPICS Small Business Hub, visit: https://www.sapics.org/sapics-small-business-hub-members

Western Cape Procurement Conference 2025

Welcome to the 12th annual gathering in Western Cape

Under the theme “Blueprint to Impact: Creating a Legacy of Growth,” this year’s conference is a call to action for all who are passionate about shaping a sustainable and prosperous future.

Amid evolving legislative frameworks and critical infrastructure and energy challenges, this event provides an essential platform for leaders, experts, and stakeholders to unite, exchange knowledge, and forge impactful partnerships.

Supported by the Western Cape Provincial Treasury and Department of Infrastructure, the conference will convene officials from municipalities and government departments, as well as prominent engineers and asset management practitioners. Together, we will explore forward-thinking strategies that address immediate needs while building resilient systems for long-term growth and economic transformation.

Developing a market for buying electrons

Credit: Casey Horner on Unsplash

To better understand the concept of “wheeling”, Opportunity sat down with the Chairman of the South African Independent Power Producers Association (SAIPPA), Brian Day, on the sidelines of the Africa Renewable Investment Summit (ARIS) in November 2024.

What is wheeling?

An example is power being generated in the Eastern Cape by an independent power producer (IPP) and power being used by a customer in Mpumalanga. When your customer and your generator are both connected directly to Eskom, you have a wheeling arrangement.

But it is not literally that same power?

It’s different electrons and it’s a book entry. It’s a commercial arrangement and there are loss factors based on the relative geographies of the two to be taken into account.

The customer has an electricity supply agreement with Eskom and the generator has a connection and use-of-system agreement with Eskom. All the electricity comes through the Eskom meter but some of that came from the IPP. The credit on the customer’s bill is enough to pay the power-purchase agreement (PPA) to the generator.

And wheeling is catching on?

Slowly, and limited to big customers. In the future, in the same way you buy pencils at the corner shop you would buy electrons. Such a market at the wholesale level is being developed, while the retail market is some way off. Developing a market for power is where we are going. Mulilo has reached financial close on two Eastern Cape projects for 260MW total for a combined off-take by Sasol and Air Liquide for their Secunda operations.

Sasol needs a lot of power for its operations, not so?

Sasol was at the forefront of wheeling, much of which was initially done between their facilities in Sasolburg and Secunda. Eskom designed wheeling largely for Sasol because it is a massive prosumer, both a consumer and a producer of power. It’s an intriguing concept in the electricity space; other companies like [timber and dissolving pulp producer] SAPPI are prosumers because they have excess heat, which is excess energy and can be converted to electricity.

What is an aggregator?

A company trying to trade electricity.

Are we moving towards having a seamless market for such trading?

We are moving there now more than ever before and in the last year there has been significant progress.

Are there obstacles?
Brian Day, Chairman of the South African Independent Power Producers Association (SAIPPA).

The Electricity Regulation Amendment Act was promulgated on 1 January 2024, with some parts postponed, despite the complaints of the South African Local Government Association (SALGA) and municipalities.

Municipalities have a distribution licence and the word in the legislation and regulations is “supply”, but that is distinct from a trading licence which is the buying and selling: it is like running a fleet of trucks on somebody else’s freeway. Some other people need to do their job too, most notably the National Energy Regulator of South Africa (NERSA).

Can municipalities protect themselves from losing future revenue by building a solar farm?

A municipality can do three things: they can procure from an IPP who builds for them, they can establish new generators themselves or they can establish wheeling frameworks so that third parties establish new generators and sell to other third parties where they don’t have the onerous task of being the balance sheet. By wheeling, they are making their “road” available to willing people.

But does the road belong to the city? Does it not belong to Eskom?

It belongs to Eskom only up to a point, but then it gets to a point where the grid belongs to the city and that’s the problem. As I said about the big Sasol wheeling projects, if both the customer and the generator are connected directly to Eskom then it works. If one or other or both are connected to a municipal grid which in turn is connected to Eskom, you then have to make these arrangements with both the entities. And that’s when it gets more difficult.

For information on the South African Independent Power Producers Association: www.saippa.org.za


Additional information:

Eskom Electricity Wheeling resource: https://www.eskom.co.za/distribution/wp-content/uploads/2022/07/20220721-Wheeling-concept_Introduction.final_.pdf

Explore South Africa’s Digital Future at the 35th Digital Transformation Summit

South Africa has made significant progress in transferring its government, businesses, and public services to digital platforms, thereby promoting inclusive growth. The key to this transition is increasing access to digital technologies and ensuring that all citizens are included in the digital world through effective regulations.

The South Africa Connect (SA Connect) effort, which began in 2018, intends to connect under-served and rural areas by linking 42,000 government buildings, including schools and healthcare facilities, by 2026. Phase 1 connected 970 government buildings in eight rural districts, laying the framework for future growth.

Phase 2, which began in late 2023, aims to connect an additional 882,000 households with an R2.4-billion investment. This phase also involves a feasibility assessment conducted in partnership with the Popular Bank of Southern Africa to identify the most effective rollout techniques. Through these initiatives, the program hopes to minimise the digital divide, promote digital inclusion, and enable residents to participate in the digital economy, thereby promoting both social and economic progress.

Overview of the event

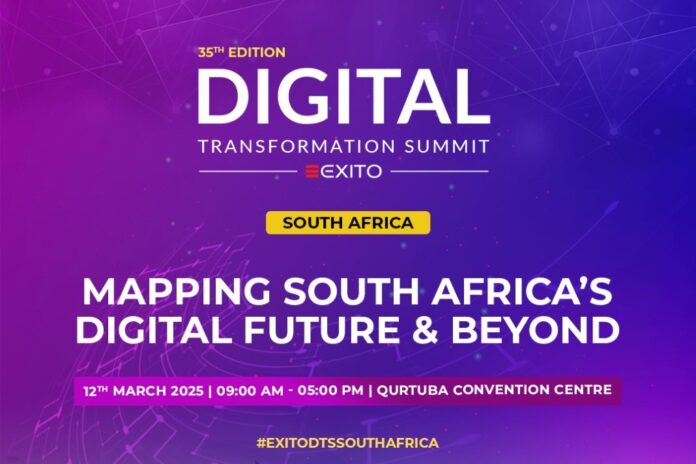
The 35th Edition of the Digital Transformation Summit is a leading global event that brings together over 300 C-Level Executives, Directors, and Heads of Technology to explore groundbreaking advancements in AI, Web 3.0, IoT, Quantum Computing, Cybersecurity, and other Fourth Industrial Revolution (4IR) technologies. Offering essential insights to help businesses navigate digital transformation, enhance operational efficiency and stay competitive in an ever-evolving digital landscape, this summit provides attendees with actionable strategies to drive meaningful change and maintain an edge in their industries. Held under the theme “Mapping South Africa’s Digital Future & Beyond,” the event will take place on 12 March 2025, from 09:00 AM to 05:00 Pm at Qurtuba Convention Centre, Johannesburg.

Who will Speak?

  • Dr Denisha Jairam-Owthar – Group Chief Information Officer, Council for Medical Schemes.
  • Khetha Cele – Group Chief Information Officer, IDFC.
  • Mahendra Beharie – Chief Information Officer, Sub Saharan Africa, DHL Express.
  • Faith Burn, Chief Information Officer, Eskom Holdings SOC Ltd.
The event will cover topics like:
  • South Africa’s Digital Future: A Roadmap for National Transformation.
  • Unlocking South Africa’s Potential: The Transformative Power of Big Data and Gen AI.
  • Navigating Sustainable Digital Transformation: Innovation, Resilience, and Economic Growth.
  • South Africa’s Digital Infrastructure: A Catalyst for Economic Prosperity.
  • From Data to Action: How Advanced Technologies Drive Customer Experience Strategies.
  • Securing South Africa’s Digital Landscape: Addressing Emerging Cyber Threats.

For more information on the 35th Edition of Digital Transformation Summit: https://digitransformationsummit.com/south-africa/


2025 Sector Insights: An overview of the energy sector in South Africa

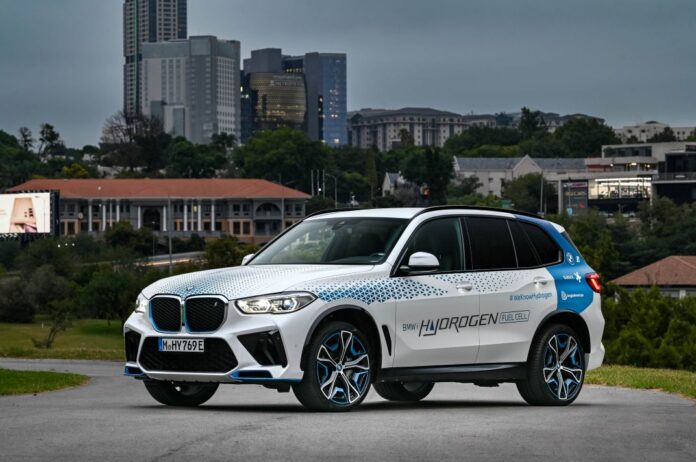
Cars powered by hydrogen are on the road. Credit: BMW

What The Economist¹ says is happening in the world, GreenCape asserts is taking place in South Africa. Both the UK newspaper and the not-for-profit company concluded within a couple of months of one another in the middle of 2024 that solar is winning. 

The Economist’s special section on the topic made the point that the progress of solar technology is so fast and so widespread that it almost doesn’t matter that there is some resistance to it: the battle is over. Some statistics put forward in the newspaper included:

  • The levelised cost of solar since the 1960s has gone down by a factor of more than 1 000
  • China’s solar panel capacity is 3.5TW
  • Battery operators in Texas recorded revenues in 2023 of $523-million
  • Whereas it took a year for the world to create 1GW of solar power in 2004, it now takes days (Source: Michael Liebreich)

Closer to home, GreenCape’s “Energy Services Market Intelligence Report 2024” noted a 52% increase in rooftop solar PV installations in South Africa, to 3.2GW from the beginning of 2022 to the first quarter of 2023. They assessed that market value at R41.6-billion and predicted that installed capacity will increase by 2030 to 10GW with a market value of R130-billion.

GreenCape also made observations about South Africa’s automotive industry. Given that the US is likely to want to pivot away trade with China, South Africa’s OEMs need to speed up the production of electric vehicles (EVs). The report noted that with many OEMs in the Eastern Cape, the creation of “large-scale renewable energy plants, such as wind and solar” would support this process. GreenCape market intelligence reports are published in partnership with UK PACT.

One of South Africa’s most successful investment projects, the Renewable Energy Independent Power Producer Procurement Programme (REIPPPP), suffered a setback in the period between 2015 and 2021 but investors are again queuing up to take a stake in greener energy.

According to the Presidential Climate Commission, the pipeline of REIPPPP projects stood at R377-billion in June 2024. Applications for the development of 4.5GW were received in 2023, sharply up from the two previous years, 135MW (2021) and 1.6GW (2022). The establishment of a one-stop shop to deal with registering projects is part of the reason for the expansion of potential new capacity.

The problem is that South Africa has now come up against the constraints of the national grid. In the most recent round of bidding for projects, the Northern Cape received fewer projects than it otherwise would have if the national grid was keeping up with increased generation potential of new projects. This gives Mpumalanga a comparative advantage. With most of South Africa’s power stations located in Mpumalanga, the issue of grid capacity does not arise.

Automotive manufacturers have not gone all in on switching to producing electric vehicles (EVs), not least because global and local consumers have been somewhat hesitant to commit fully to EV options. There have also been calls from the industry for national government to give guidance in terms of how much support can be expected for the rolling out of incentives to produce EVs and in terms of providing supporting infrastructure, such as charging points.

Ford Motor Company, in announcing a range of investments at their sites in Tshwane and Gqeberha, set aside an amount of R5.2-billion for the production of the hybrid-electric Ranger bakkie to be built in Gauteng. Mercedes-Benz South Africa now makes two plug-in hybrid-electric vehicles at its East London plant, although only one of those is sold in South Africa.

The Automotive Industry Development Centre (AIDC) Eastern Cape is taking steps to prepare the province for EVs through its eMobility and Climate Change Support Business Unit. A high-profile aspect of the unit’s work has been the creation of EV charging stations in different parts of the Eastern Cape, including Gqeberha, East London and the Tsitsikamma. Education, research and the promotion of the idea of EV travel, including through the conversion of bus fleets, form important parts of the work of the unit.

Wheeling

Another big change that has come to South Africa’s energy landscape is the concept of “wheeling”. This entails power being generated specifically for a customer and “wheeled” along the grid to that customer from a supplier of energy. For this to work the grid has to be neutral and for that to be a reality, Eskom had to be unbundled, a process that has begun.

The model might entail a high-energy-use company entering a contract with a renewables company to supply it, as is the case with the Impofu Wind Farm complex comprising three 110MW facilities in the Eastern Cape, which will supply energy to Sasol and Air Liquide in Mpumalanga. Enel Green Power and Red Cap are building the R9-billion project. Another example is the joint venture called Envusa Energy, which is the new partnership between EDF Renewables and Anglo American.

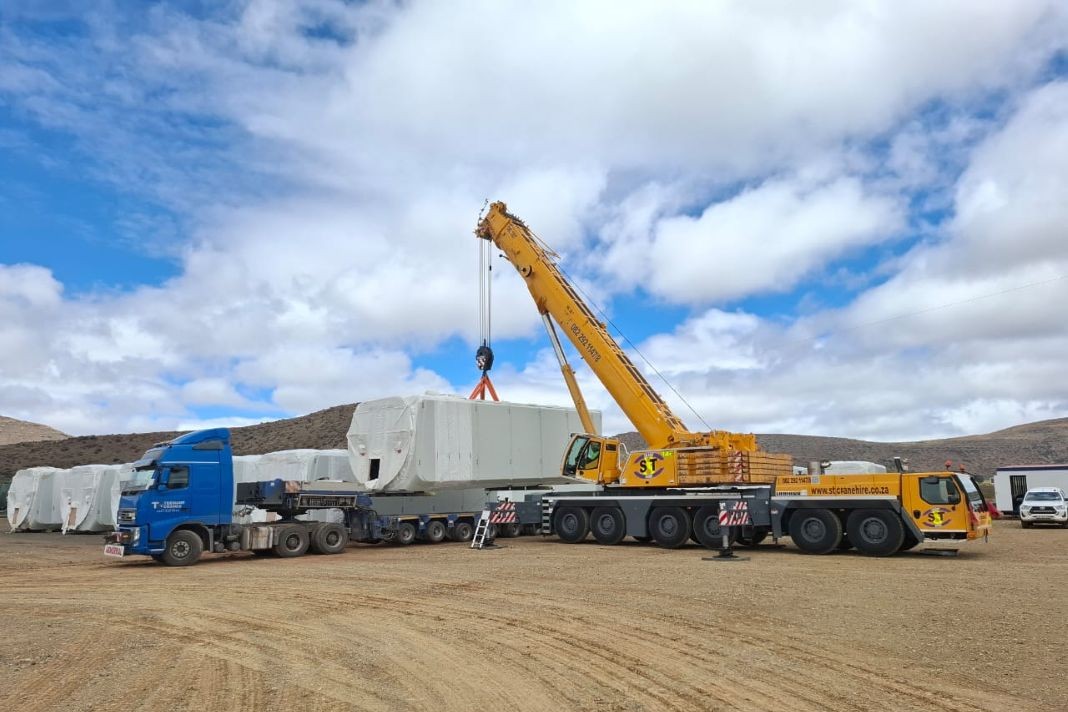
Moving massive wind turbines can be a tricky business. Credit: Nordex Energy

Envusa Energy is putting up 50 Nordex turbines on Umsobomvu and Hartebeesthoek wind farms which form part of the Koruson 2 cluster, a blended wind and solar project which is partly in the Eastern Cape and partly in the Northern Cape.

An alternate model is emerging with the creation of energy aggregators, companies that can buy and sell at scale. National regulations on how much electricity private generators could sell fell away in 2023 and that has liberalised and turbo-charged the market. Some of the new aggregator companies include Discovery Green, NOA, Etana Energy and Lyra Energy.

Battery storage is increasingly becoming an important part of hybrid projects and a move in November 2023 by the JSE, Africa’s biggest stock market, signalled another landmark on the renewable energy landscape.

JSE Ventures has initiated a Voluntary Carbon Market together with US company Xpansiv, with the aim of creating a market for carbon credits.

Wind power is not being left behind, though. In Mpumalanga, Seriti Green has broken ground on a project that will deliver 750MW of wind from 130m towers when it is complete. In addition, the hybrid model will include 100MW of solar and 800MW of battery.

The greater Humansdorp Jeffreys Bay area hosts no fewer than 13 wind farms so the announcement in March 2024 that Nordex Energy South Africa is to start making concrete tower sections at a manufacturing facility in Humansdorp makes economic sense.

Up to 300 jobs will be created and work at the tower factory is expected to start in Q1 2024 with the first set of turbines due to be installed in the second half of the year. Having invested in the Eastern Cape since 2013, Nordex Energy South Africa boasts a significant footprint in the province, including a warehouse in Gqeberha and 573MW of installed capacity across five wind-power plants.

The latest large resources company to announce a 20-year power-purchase agreement is Richards Bay Minerals. Khangela Emoyeni Wind Farm will supply the miner with 140MW from the huge renewable-energy generator that rolls over a series of mountains on the edge of the Western and Northern Cape provinces.

Certain manufacturing companies that have access to biomass that results from the manufacturing process, such as woodchips for Sappi and bagasse in the case of sugar producers such as Tongaat Hulett and Illovo, are in a position to produce their own energy.

However, there are industries where signing offtake agreements with renewable energy producers is the more logical route to take. In fact, even PGM miner Ivanhoe Mines, despite having its own plans to produce solar power, has signed an offtake agreement with Renergen. 


¹ Visit The Economist at https://www.economist.com/topics/the-world-ahead-2025